Can net lease bonus depreciation offset W-2 income?
Not automatically. Rental losses are generally passive and normally cannot offset wages. Exceptions and special allowances have specific requirements; real estate professional status alone does not establish material participation. Ask your tax adviser to test your participation, income, basis and at-risk limits before treating a property deduction as a reduction of employment income.
Can a net lease property qualify for 100% bonus depreciation?
Eligible components of a net lease property can qualify, but land and the entire 39-year building generally do not. A cost segregation study may identify 5-, 7-, and 15-year assets that are eligible under the current federal rules. Taxpayer-level limitations and elections can change the usable deduction.
Is bonus depreciation 100% for NNN property in 2026?
Current federal law generally allows 100% bonus depreciation for qualified property acquired and placed in service after January 19, 2025. Acquisition timing, written binding contracts, placed-in-service dates, elections, and transition rules matter, so an investor should confirm the applicable percentage with a tax adviser.
Does the purchase price of an NNN building qualify?
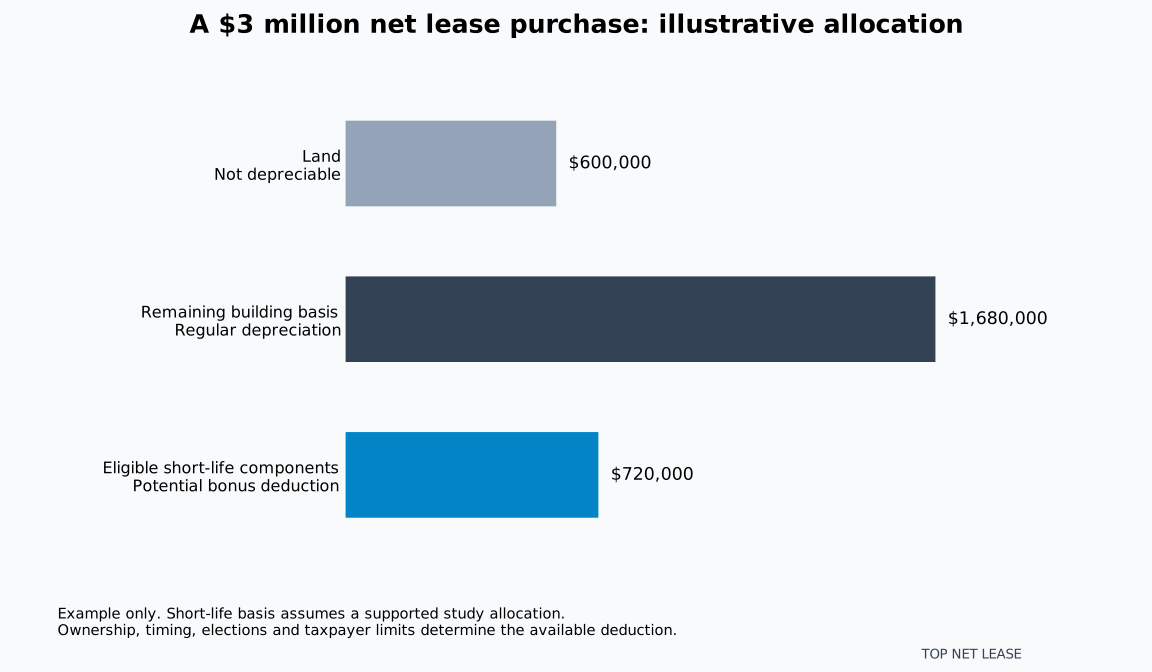
Not in full. The purchase price must first be allocated among land, the building, and other assets. Land is not depreciable, the structural building is generally 39-year property, and qualifying shorter-life components may be eligible for accelerated depreciation.
Do gas stations qualify for bonus depreciation?
Many fuel and convenience-store acquisitions contain substantial equipment and land improvements that may have shorter recovery periods. Certain qualifying retail motor-fuels facilities may also receive 15-year treatment, but the statutory gross-receipts and floor-space tests must be documented rather than assumed from the property label.
Do car washes qualify for 100% bonus depreciation?
A car wash can contain significant equipment, specialized systems, paving, and other shorter-life components. Eligibility depends on ownership, tax classification, acquisition and placed-in-service dates, and a defensible allocation or cost segregation analysis; the entire property is not automatically deductible.
Who depreciates tenant improvements in a net lease?
Usually the taxpayer that owns and capitalizes the improvement claims depreciation. If a tenant pays for and owns an improvement, the landlord generally cannot depreciate that tenant-owned basis. Lease language, allowances, reimbursements, and ownership at lease end should be reviewed carefully.
Can used NNN property qualify?
Yes. Eligible used property can qualify when it is new to the buyer and satisfies the prior-use, related-party, acquisition, and qualified-property rules. A newly purchased building is not disqualified merely because it was previously occupied.
Is a cost segregation study required?
The tax law does not use a blanket rule that every claim requires a formal study, but a quality engineering-based study is the common way to identify, value, and document shorter-life components in an acquired commercial property. The level of support should be proportionate to the deduction and audit risk.
Is bonus depreciation recaptured when the property is sold?
Accelerated depreciation reduces basis and can create Section 1245 ordinary-income recapture or other depreciation-related gain when assets are sold. The result depends on each asset and transaction. A 1031 exchange does not automatically defer recapture on personal-property components.
Can bonus depreciation be used with a 1031 exchange?
Potentially. Section 1031 addresses gain deferral on qualifying real property, while bonus depreciation accelerates deductions for eligible replacement-property components. Carryover basis, additional basis, boot, asset classification, and recapture must be coordinated before closing.
Do all states allow 100% bonus depreciation?
No. States may conform, decouple, or require an addition followed by later deductions. Federal and state basis schedules should be modeled separately for the property and ownership entity.